When Paperless Statements Void Your Right to Challenge a Processing Error
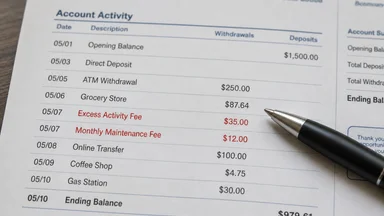
Switching to paperless bank statements seems convenient. Fewer trees die. Your inbox stays cleaner. The bank's marketing materials call it smart, modern, green. But buried in the account agreement you clicked through is a clause that can strip away your right to challenge a processing error. The moment that PDF goes live online, a federal 60-day clock starts ticking—whether you open it, see it, or even know it exists. Miss that window, and the bank can legally keep money that was never supposed to leave your account.
The Paperless Trap Buried in Your Account Agreement
Banks love paperless statements for reasons that have little to do with the environment. Electronic delivery cuts printing and postage costs by an estimated US$1–3 per account per month. For a large retail bank, that adds up to tens of millions in annual savings. But the cost savings come with a hidden trade-off for the customer: the bank no longer mails a physical copy of your statement to your home address.
That shift matters because of how Regulation E defines the start of the error-resolution clock. Under the Electronic Fund Transfer Act, a consumer has 60 days from the date a periodic statement is sent or made available to notify the bank of an unauthorized transfer or processing error. When you receive a paper statement by mail, the 'sent' date is clear: the postmark, or the date printed on the statement envelope. But when you opt for electronic delivery, the bank often defines 'made available' as the moment the statement is posted to your online account portal.
The fine print in most paperless enrollment agreements states that you agree to receive electronic communications and that the bank satisfies its delivery obligation by posting the statement online. Some agreements go further: they explicitly waive any requirement to mail a physical copy. If you do not log in for a month, or if the email alert lands in your spam folder, the statement is still considered 'received' under the contract. That means the 60-day window can expire before you ever lay eyes on the document.
Consumer advocates have called this the paperless trap. The CFPB's 2024 report on digital banking practices noted a rise in complaints from consumers who discovered errors only after the dispute window had closed. In many of those cases, the bank's first response was a form letter citing the 60-day rule and denying the claim as untimely. The consumer had no physical record to prove when the statement actually reached them—because there was no physical record at all.
How a 1978 Regulation Became a Digital Loophole
The Electronic Fund Transfer Act of 1978 was written for an analog world. Congress designed it to protect consumers when money moved electronically—through ATMs, point-of-sale terminals, and early direct deposit systems. The dispute process assumed a paper trail: a printed receipt from the ATM, a monthly statement mailed to the home, a signature acknowledging receipt. Regulation E, the implementing rule, gave consumers 60 days from the mailing of a periodic statement to spot and report errors.
For two decades, that framework worked reasonably well. Banks mailed statements, consumers received them, and the postmark provided an objective timestamp. If a statement went missing, the consumer could call the bank and request a duplicate, and the 60-day clock was usually measured from the original mailing date—giving some leeway. But as online banking took off in the late 1990s and early 2000s, banks began offering electronic statements as an alternative, then as the default.
Regulation E was amended in 1998 to accommodate electronic disclosures, but the key language remained anchored to the concept of 'sending' or 'making available.' The Federal Reserve's Official Staff Interpretation at the time stated that a financial institution could make a periodic statement available electronically if the consumer agreed. The interpretation did not specify when the statement was deemed 'received' for purposes of starting the 60-day clock. Banks filled that gap themselves in their account agreements.
The result is a patchwork of state and federal court rulings. Some courts have held that posting a statement online constitutes delivery. Others have required the bank to show that the consumer actually accessed the statement. In Johnson v. Chase Bank (2022), the U.S. District Court for the Central District of California ruled that Chase's electronic delivery terms—which stated that statements are 'deemed delivered' when made available online—were enforceable, and the consumer's 65-day delay was fatal to the claim. The court noted that the consumer had agreed to those terms when enrolling in paperless statements. Other courts have split, creating uncertainty for consumers and banks alike.
The 60-Day Clock That Starts Without You
Regulation E's 60-day window is the single most important deadline in consumer electronic banking. It governs errors ranging from unauthorized withdrawals to incorrect fees to duplicate transactions. If you report a problem inside that window, the bank must investigate and, in most cases, provisionally credit your account within 10 business days. If you report it after day 60, the bank has no obligation to investigate at all. It can simply deny the claim and keep the money.
The clock starts on the date the periodic statement is 'sent or made available.' For paper statements, that is straightforward. For electronic statements, banks have adopted a range of definitions. Some use the date the statement is generated and posted to the portal. Others use the date an email notification is sent—even if the email bounces or lands in spam. A 2023 study by the Consumer Federation of America found that roughly 40 percent of large banks define 'made available' as the posting date, with no requirement that the consumer receive or open the email.
Email alerts are notoriously unreliable. Mimecast's 2024 Email Security Report estimated that 15–20 percent of legitimate bank notifications are filtered into spam folders by major providers. If your bank sends a statement alert on the 1st of the month and you do not see it until the 15th, you have already lost 14 days. If you do not see it at all, you could lose the entire window. The bank's system logs the statement as 'delivered' the moment it is posted, and that timestamp is what the bank's compliance team will produce if you later dispute an error.
The CFPB's complaint database includes dozens of entries where consumers describe discovering an error months later—often during tax season or when a larger transaction triggered a review. By then, the 60-day window was long closed. One consumer reported that a fraudulent debit of roughly US$400 was never flagged because the statement was available online but the email alert went to spam. The bank denied the claim, citing the 60-day rule. The consumer had no paper statement to fall back on.
When Opting Out Means Opting Into Risk
Enrolling in paperless statements is usually a one-click process during online account setup. Opting back into paper delivery is often far more cumbersome. Many banks require a separate form, a phone call, or a 30-day waiting period. Some hide the opt-out option in a dense account agreement that few consumers read. The Federal Reserve Board's 2024 consumer survey found that 72 percent of respondents who had paperless statements did not know they could request paper copies without charge.
The cost of paper delivery is minimal for the bank—perhaps US$1–2 per month per account—but the friction of reversing the choice is deliberate. Banks have a financial incentive to keep customers paperless. A 2023 settlement between the Consumer Financial Protection Bureau and Wells Fargo highlighted this practice. The CFPB alleged that Wells Fargo misled consumers about the terms of its paperless program, including failing to clearly disclose that electronic statements would be deemed 'received' when posted. Wells Fargo paid a US$1 billion penalty for a range of consumer abuses, but the paperless disclosure issue was a smaller part of a larger pattern.
The FDIC's 2024 advisory on electronic banking disclosures urged institutions to provide clear, conspicuous information about when a statement is considered delivered and how consumers can opt out. But advisories are not binding rules. The advisory specifically noted that banks should not place the burden on consumers to discover errors through 'active monitoring' of online portals. Yet that is exactly what the current framework does. If you do not log in regularly, you may never know that an error occurred until it is too late.
Some consumer advocates recommend requesting paper statements in writing and keeping a copy of the request. Others suggest setting a recurring calendar reminder for the date your statement is typically released—often the same day each month—and logging in to download and save a PDF with a timestamped filename. But even that system depends on the consumer remembering to act. A single missed month can be enough to lose the right to dispute.
The 'Critical Third Party' Oversight Gap
Banks rarely run their statement portals in-house. Most contract with third-party vendors that handle digital document delivery, email notifications, and online account access. These vendors are what UK regulators call 'critical third parties'—firms whose failure could disrupt the financial system. As of July 2026, the Bank of England, Prudential Regulation Authority, and Financial Conduct Authority have begun overseeing designated critical third parties under a new regulatory framework.
The oversight gap is that consumers have no direct recourse against these vendors. If a vendor's email system fails to send a statement alert, or if the portal goes down on the day a statement is posted, the consumer cannot sue the vendor for a missed deadline. The bank is the consumer's only point of contact, and the bank's standard response is to point to its own terms and conditions, which typically disclaim liability for third-party service interruptions.
The Financial Conduct Authority in the UK is still reviewing error-disclosure rules for electronic statements. A 2025 consultation paper proposed requiring banks to send a separate, non-spam-filterable notification when a statement is made available—perhaps via text message or push notification through a mobile app. Industry groups pushed back, citing the cost of developing and maintaining multiple notification channels. The FCA has not yet issued a final rule.
In the United States, the CFPB proposed a rule in 2025 that would require banks to provide a 'digital receipt'—a downloadable, timestamped summary of each electronic statement—and to send a confirmatory email when the statement is posted. The rule is still in the comment period and faces opposition from banking trade associations that argue it would increase compliance costs. Even if finalized, the rule would likely take years to implement. Until then, the critical third-party oversight gap remains.
Four Steps to Lock in Your Paper Trail
While regulators debate, individual consumers can take concrete steps to protect their dispute rights. These four measures are not foolproof, but they shift the burden back toward the bank and create a paper trail that a court or regulator can follow. (Note: These are suggestions, not guarantees; outcomes depend on individual circumstances and applicable law.)
First, request paper statements in writing. Send a letter to your bank's customer service address—not an email—requesting that all future periodic statements be sent by U.S. mail. Keep a copy of the letter and the certified mail receipt. Some banks will honor the request; others may push back or require a fee. If the bank charges for paper statements, ask for a fee waiver based on your preference, but be prepared to pay a modest amount. The cost is insurance against a much larger loss.
Second, set a recurring calendar reminder for statement release. Most banks release statements on a predictable schedule—often the same day each month. Mark that day on your calendar and set a recurring reminder to log in and download the PDF. Name the file with the date and account number, and save it to a folder you back up. This creates a timestamped record that you can produce if a dispute arises.
Third, use certified mail for error disputes. If you discover an error—even one that seems minor—send a written dispute by certified mail, return receipt requested, to the address specified in your account agreement for error notices. Do not rely on the bank's online chat, email, or phone system. Regulation E requires the bank to act on a written notice, and certified mail gives you proof of delivery and a date stamp that cannot be disputed.
Fourth, review account activity every 30 days. Set aside time once a month to go through each transaction on your statement, comparing it against your own records. If you see something unfamiliar, investigate immediately. The 60-day window does not wait for you to finish your tax return or reconcile your budget. A quick monthly review can catch errors early enough to preserve your rights.
Why Regulators Are Finally Paying Attention
The paperless trap has been a known issue among consumer advocates for years, but regulatory attention has accelerated in the mid-2020s. The CFPB's proposed rule on digital receipts, published in 2025, would require banks to provide a downloadable, machine-readable record of each electronic statement and to send a separate notification—via email or text—when the statement is made available. The rule is still in the comment period, and banking industry groups have argued that the requirement is redundant and costly.
In the U.S. Senate, the Banking Committee held a hearing in early 2026 on consumer technology and banking disclosures. Witnesses included state attorneys general who have been investigating unfair or deceptive practices related to electronic statements. Several state AGs have filed civil investigative demands seeking information about how banks define 'delivery' and whether consumers are adequately informed of the 60-day deadline. No federal legislation has been introduced, but the hearing signaled growing bipartisan concern.
Industry pushback has been predictable. The American Bankers Association and the Consumer Bankers Association have argued that paperless statements are a convenience that consumers prefer, and that additional disclosure requirements would increase costs that are ultimately passed on to customers. They also point out that most consumers never encounter an error, and that the existing system works well for the vast majority. That is true, but the minority who are harmed by the paperless trap face potentially significant financial losses.
Resolution is likely years away. The CFPB's rulemaking process is slow, and any final rule will almost certainly face legal challenges from industry trade groups. In the meantime, the burden remains on consumers to understand the terms they agreed to and to take proactive steps to protect their rights. The paperless trap is a structural issue—the unintended consequence of a 1978 regulation meeting a 21st-century delivery system. Until the rules catch up with the technology, the safest bet is to keep a paper trail.
This article is for informational purposes only and does not constitute legal or financial advice. Readers should consult a qualified professional for advice tailored to their individual circumstances.